
We've been helping Australians for 100 years
We explain what you need to know about townhouses and insurance.
Share this story:

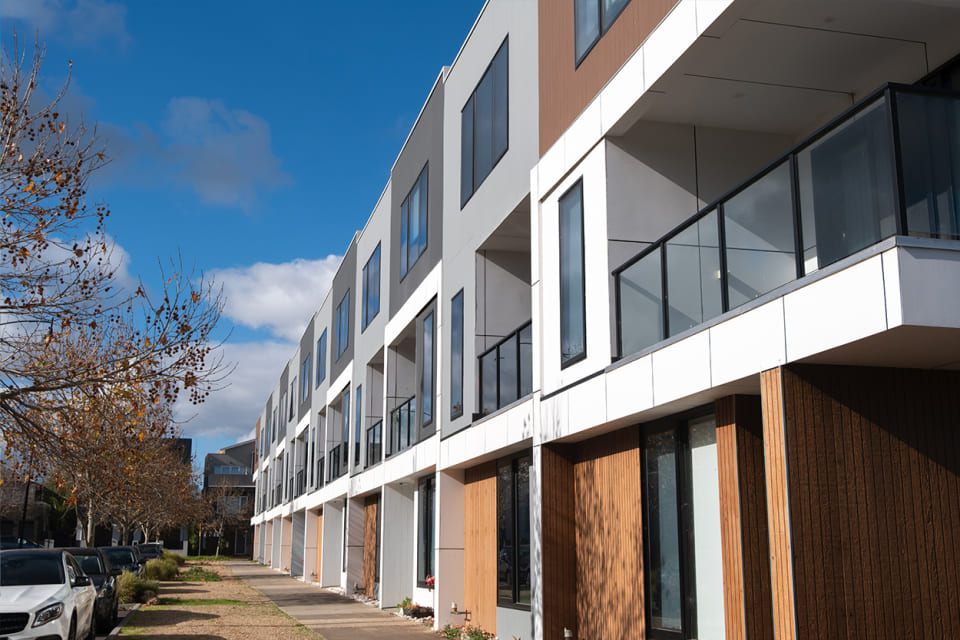
If you’ve strolled down an inner-city suburb recently, chances are you’ve walked past a townhouse or two. Townhouses can be single story or multi story, freestanding or attached; it’s also common for multiple townhouses to share a single lot, all with a similar facade and layout.
The key thing to know is that many attached townhouses are strata-titled, with common property and shared walls. These are the residences that usually require a little more thought about what insurance might be required or considered.
If you have a strata property, your townhouse (and your neighbour’s) could require strata insurance (also known as Residential Strata Insurance). Strata insurance helps cover shared or common property, including building fixtures, recreation areas and public liability. A good example is when two properties share a wall.
Sometimes, people living in an attached townhouse may choose to take out a personal building insurance policy to cover permanent fixtures that aren’t covered by strata insurance.
Think of strata insurance as insurance for you and your neighbours that covers the collective interests of you and the other owners in the strata scheme and is also a legal requirement.
Home insurance, like buildings insurance and contents insurance, are policies that cover your personal assets. Buying home insurance policies such as these is a choice, rather than a requirement.
Contents insurance is another key consideration for townhouse owners and renters. Contents insurance typically helps cover the personal belongings you keep inside your home (including furniture, appliances, carpets, electronics and more) in the event they’re lost, damaged or destroyed because of an insured event, like a fire, flood or storm.
Be sure to carefully read the relevant Product Disclosure Statement (PDS) to find out what is and isn’t covered by a policy. In addition to all the limits and exclusions that apply to a type of cover, the PDS also includes helpful definitions and common claim scenarios (and how they’re managed), to give you an idea of what to expect.
Information is current as at the date of publication and may be subject to change. All content on the NRMA Insurance Blog is intended to be general in nature and does not constitute and is not intended to be professional advice. It does not take into account your individual objectives, financial situation or needs. References to third-party organisations, products, services or brands on the NRMA Insurance Blog are for informational purposes only and do not imply any affiliation with or endorsement by NRMA Insurance, unless expressly stated otherwise.